For many Nigerians, owning a home remains a major financial ambition. However, rising property prices, expensive building materials and the difficulty of raising the full purchase price have made homeownership increasingly challenging.
Many working Nigerians spend years paying rent while hoping to save enough money to purchase their own homes.
But what if you could purchase a residential property and spread the payment over several years instead of paying the entire amount upfront?
The Federal Government has highlighted two mortgage financing opportunities that could help eligible Nigerians move closer to homeownership:
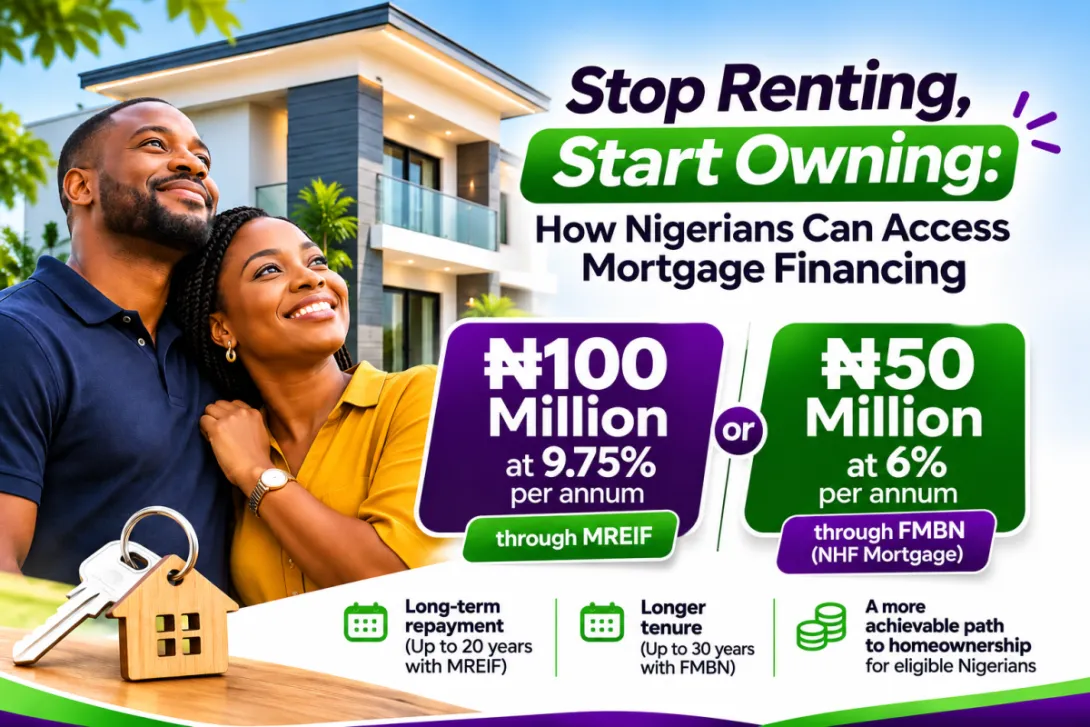
- Up to ₦100 million at a fixed interest rate of 9.75% per annum through the MOFI Real Estate Investment Fund (MREIF).
- Up to ₦50 million at 6% interest per annum through the Federal Mortgage Bank of Nigeria's National Housing Fund (NHF) mortgage facility.
These programmes offer different financing structures, eligibility requirements and repayment periods. Understanding the differences can help prospective homeowners determine which option may suit their circumstances.
1. The ₦100 Million Mortgage at 9.75% Through MREIF
The MOFI Real Estate Investment Fund (MREIF) provides long term mortgage financing to eligible Nigerians seeking to purchase residential properties.
The facility offers:
- Maximum mortgage: ₦100 million.
- Interest rate: 9.75% per annum, fixed.
- Repayment period: Up to 20 years.
- Initial equity contribution: From 10%, subject to the participating lender's requirements.
- Applicants: Eligible Nigerian citizens who meet the applicable income and credit requirements.
The programme is designed to make it easier for qualified Nigerians to purchase homes without raising the entire property value upfront.
For example, if you intend to purchase a property worth ₦50 million, a 10% initial contribution would amount to ₦5 million, while the remaining ₦45 million could potentially be financed through a mortgage, subject to approval and the lender's conditions.
The actual equity contribution, fees and repayment amount will depend on the participating financial institution and the approved mortgage terms.
2. The ₦50 Million Mortgage at 6% Through FMBN
Another opportunity is available through the Federal Mortgage Bank of Nigeria (FMBN) under the National Housing Fund.
Eligible NHF contributors can access mortgage financing of up to ₦50 million at an interest rate of 6% per annum, with repayment extending to a maximum of 30 years.
The facility can be used to:
- Purchase a residential property.
- Build a personal home.
- Improve an existing residential property.
- Renovate a qualifying home.
To qualify, applicants generally need to be Nigerian citizens, have contributed to the National Housing Fund for at least six continuous months and demonstrate a regular source of income sufficient to support repayment.
Applications are processed through accredited and licensed Primary Mortgage Banks.
This option may be particularly attractive to eligible NHF contributors who want a lower interest rate and a longer repayment period.
3. What Is the Difference Between the Two Mortgage Options?
Both facilities are designed to improve access to homeownership, but their structures differ.
| Feature | MREIF Mortgage | FMBN NHF Mortgage |
|---|---|---|
| Maximum financing | ₦100 million | ₦50 million |
| Interest rate | 9.75% per annum | 6% per annum |
| Maximum repayment | 20 years | 30 years |
| Main eligibility | Qualified Nigerian citizens | Eligible NHF contributors |
| Application channel | Participating financial institutions | Accredited Primary Mortgage Banks |
The best option depends on your income, employment status, NHF contribution history, property requirements and ability to meet the repayment obligations.
A lower interest rate does not automatically mean every applicant will qualify. Your financial circumstances and the property's documentation will still be assessed.
4. Who Should Consider Applying?
These mortgage opportunities may be worth exploring if you:
- Are currently paying rent and want to own your home.
- Have a regular and verifiable source of income.
- Want to purchase a completed residential property.
- Have sufficient funds for the required initial contribution.
- Are an eligible National Housing Fund contributor.
- Want to spread the cost of homeownership over several years.
Married applicants may also explore joint applications where permitted, potentially combining their incomes to improve their borrowing capacity.
The MREIF programme also allows eligible Nigerians in the diaspora to explore homeownership opportunities, subject to the applicable lender's requirements and repayment arrangements.
5. Important Things to Consider Before Taking a Mortgage
A mortgage is a financial commitment, not a grant or free housing programme. You are required to repay the amount borrowed according to the agreed terms.
Before applying, consider the following:
Your income: Ensure that the proposed monthly repayment is affordable and does not place excessive pressure on your finances.
Your initial contribution: Budget for the required equity contribution and other applicable transaction costs.
Property documentation: The property must satisfy the lender's title and legal requirements.
Additional charges: Ask about insurance, valuation, legal fees, processing fees and other applicable expenses.
Repayment period: Understand the total financial commitment over the entire repayment period.
Property suitability: Confirm that the property meets your residential needs and the lender's requirements.
Do not commit to purchasing a property until you understand the mortgage conditions and have confirmed that the property is acceptable to the financing institution.
6. How Can You Take the First Step?
If you are interested in either mortgage option, start by assessing your eligibility and financial capacity.
For MREIF, visit the official mortgage platform and explore the participating financial institutions.
For the FMBN NHF mortgage, confirm your contribution history and approach an accredited Primary Mortgage Bank.
You should also identify suitable residential properties and ensure that their ownership documents are available for verification.
Remember that mortgage approval is subject to assessment. Being eligible to apply does not automatically guarantee approval or access to the maximum loan amount.
Conclusion: Homeownership May Be Closer Than You Think
For Nigerians who have spent years renting or postponing their homeownership plans, these mortgage facilities offer opportunities worth exploring.
With financing of up to ₦100 million at 9.75% through MREIF and up to ₦50 million at 6% through FMBN's NHF mortgage facility, eligible Nigerians have additional pathways towards owning residential property.
The important thing is to understand the requirements, assess your financial capacity and identify a property that meets the relevant financing conditions.
You do not necessarily have to wait until you have saved the entire purchase price before exploring homeownership.
At LandMall, we help prospective homeowners explore property opportunities and make informed real estate decisions.
Are you ready to take the next step towards owning your home?
LandMall: Find Your Property. Invest With Insight.
Visit LandMall.ng to explore available residential properties.
OFFICIAL INFORMATION AND APPLICATION RESOURCES
MREIF Mortgage Facility
Website: www.mreif.com.ng
Federal Mortgage Bank of Nigeria
Website: www.fmbn.gov.ng
Prospective applicants should confirm current eligibility conditions, participating institutions, available funding and applicable charges directly with the relevant institution.